Short answer: UAE corporate tax starts from accounting profit, then adds back what the law doesn't allow: 50% of entertaining clients and suppliers, fines, donations to bodies not on the qualifying list, dividends booked as expenses, personal costs and the costs of earning exempt income. Exempt income, such as a dividend from a UAE company, comes off. Tax is 0% on the first AED 375,000 and 9% above. An AI agent can build the adjustment from the trial balance and GL.
The add-backs themselves are well known. The work is finding them: a fine booked as a government fee, a dividend in miscellaneous expenses, the owner's family party in entertainment.
Here are the rules from a recent tutorial, then an agent building the adjustment for a Dubai contractor's year from four files.
The tutorial this is based on
DON'T CLAIM EVERYTHING! UAE Corporate Tax Warning by CA M F Khan (Export & Global Tax Expert), published 28 August 2026 (in English). A 17-minute run through the add-backs, with worked figures for each: entertainment, donations, exempt income, owner costs and mixed-use costs.
How do you get from accounting profit to taxable income?
- Start from the accounting profit in the financial statements. The add-backs go in the return as other adjustments.
- Entertainment: add back 50% of what you spend entertaining clients, suppliers and other business partners. Staff events stay deductible; an owner's family party is added back in full.
- Donations: add back donations to bodies that are not Qualifying Public Benefit Entities.
- Exempt income: deduct exempt income, such as a dividend from a UAE company, and add back the costs of earning it, such as legal fees for that stake.
- Distributions and owner pay: add back dividends booked as expenses. An owner's salary must be for real work, at market value.
- Personal and mixed-use costs: add back personal costs in full and the personal share of mixed-use ones, such as 40% of a phone used 60% for business.
- Add back fines and penalties, corporate tax itself, recoverable input VAT and bribes. Tax is 0% on the first AED 375,000 of taxable income and 9% above.
Where it usually goes wrong
- A fine booked under "Government fees", where nobody looks for it.
- A dividend to the owner booked as an expense.
- Staff and client entertainment in one account, so 50% is applied to all of it or to none of it.
- Fees for an investment whose dividend is exempt, left in the deductions.
- The owner's personal costs, and the personal share of the owner's phone or car.
- Liquidated damages under a contract added back as if they were a fine.
How an AI agent does it from Slack
We gave the agent four files for a made-up Dubai building-services contractor, Sidra Peak Technical Services: the trial balance for the year to 30 June 2026, the admin expenses GL, the donations register and a list of payments to or for the owner. Every company, name, tax number and amount in these files is made up. The agent works in Slack, where it shows up as Mnemio AI, because Accountant AI is built on Mnemio AI.
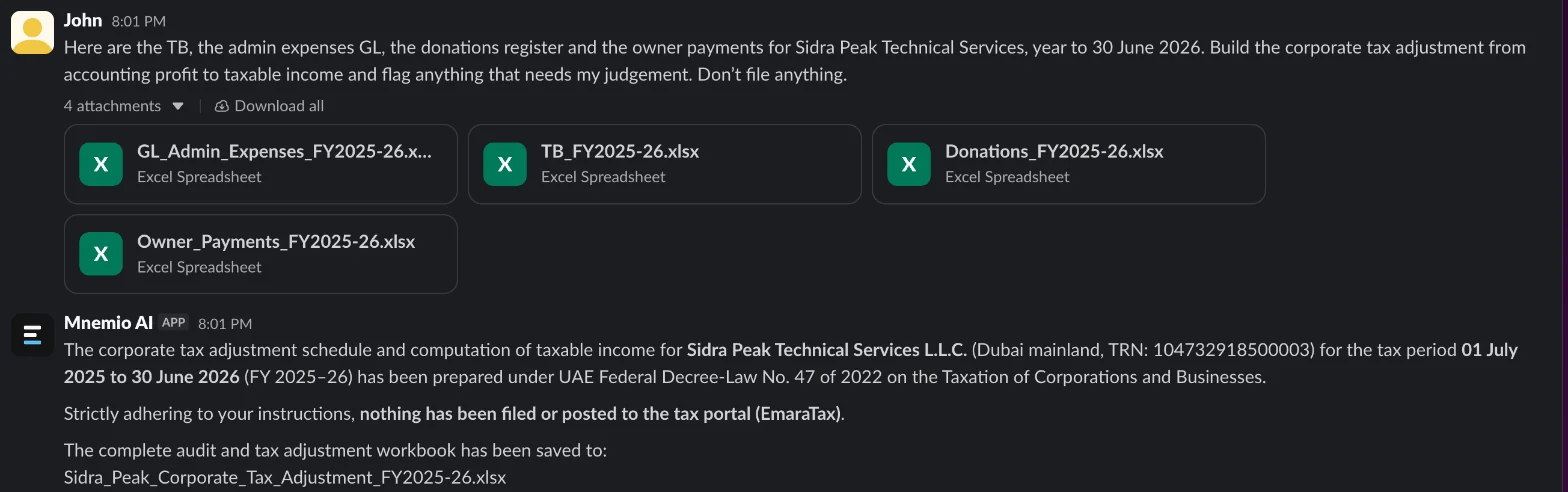
What the agent did
- Started from accounting profit of AED 1,354,123.96 in the trial balance and added back the AED 38,970 corporate tax expense.
- Split the entertainment account: 50% of the AED 48,580 spent on clients, consultants and suppliers added back, the AED 32,650 of staff events kept in full, and the owner's son's birthday party (AED 20,000) added back in full.
- Found an AED 5,000 traffic fine and an AED 2,500 municipality fine booked as government fees, and added them back. Kept AED 42,000 of liquidated damages as compensation under a contract.
- Added back an AED 300,000 dividend to the owner booked in miscellaneous expenses.
- Deducted the AED 240,000 exempt dividend from a UAE company and added back the AED 30,000 of legal and advisory fees spent on that stake.
- Added back the owner's family holiday, 40% of the owner's phone and AED 20,000 of donations to bodies not on the qualifying list.
- Worked out taxable income of AED 1,570,883.96 and tax of AED 107,629.56, flagged the owner's AED 660,000 salary for a market-value check, and filed nothing.
- Asked whether the owner's own 60/40 phone estimate is enough, it said no and listed what to keep: a signed memo on the split, the contract and invoices in the company's name, and itemised bills for sample months. Some of the articles it quoted in that answer need checking.
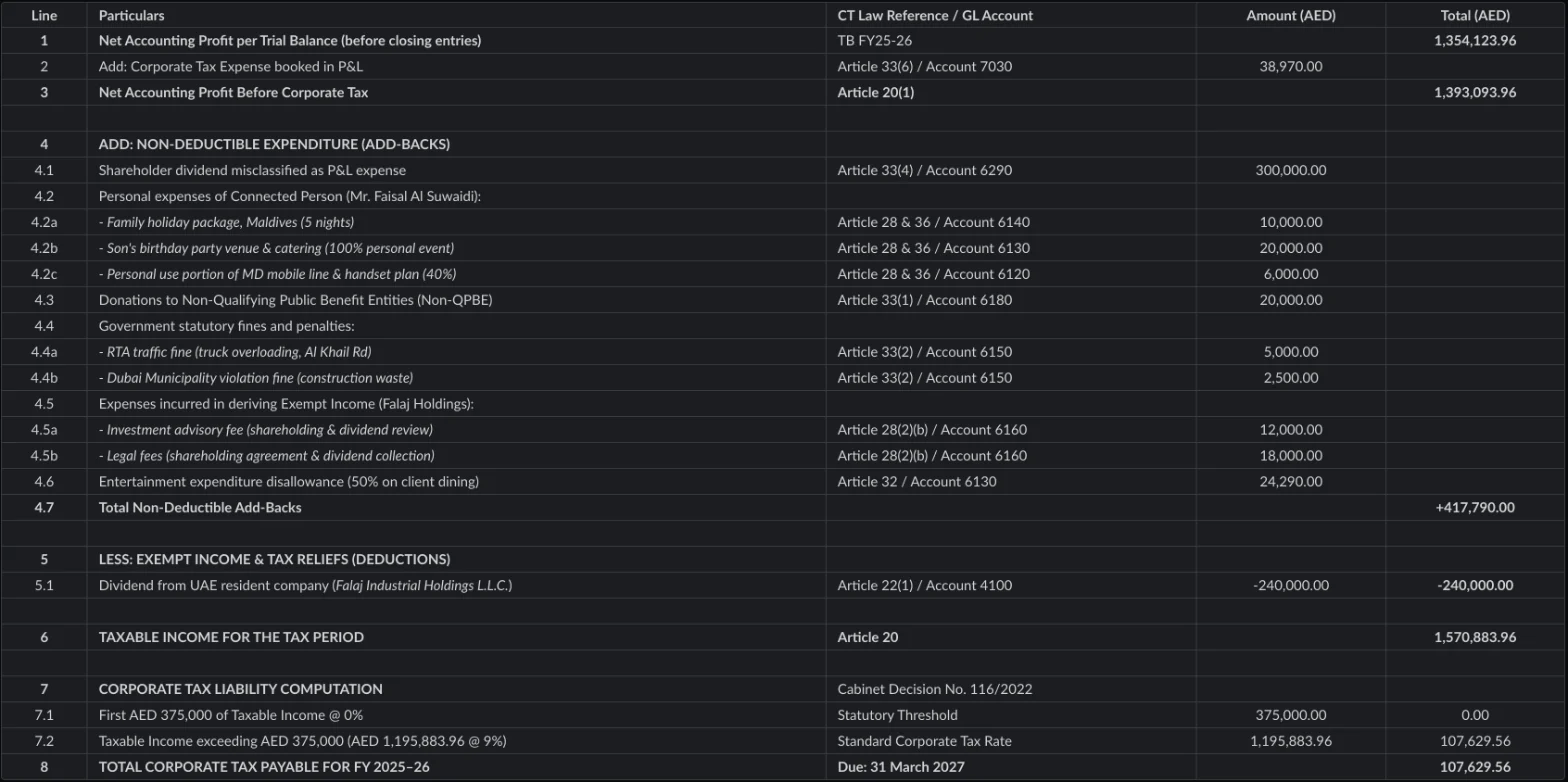
What it found
| Adjustment | AED | Treatment |
|---|---|---|
| Accounting profit | 1,354,123.96 | Starting point |
| Dividend to the owner booked as an expense | 300,000.00 | Added back |
| Exempt dividend from a UAE company | (240,000.00) | Deducted |
| Corporate tax expense | 38,970.00 | Added back |
| Owner's personal costs and 40% of the phone | 36,000.00 | Added back |
| Fees spent on the exempt dividend's stake | 30,000.00 | Added back |
| Client and supplier entertainment, 50% of 48,580 | 24,290.00 | Added back; staff events kept |
| Donations to bodies not on the qualifying list | 20,000.00 | Added back |
| Fines booked as government fees | 7,500.00 | Added back; contract damages kept |
| Taxable income | 1,570,883.96 | Tax AED 107,629.56 |
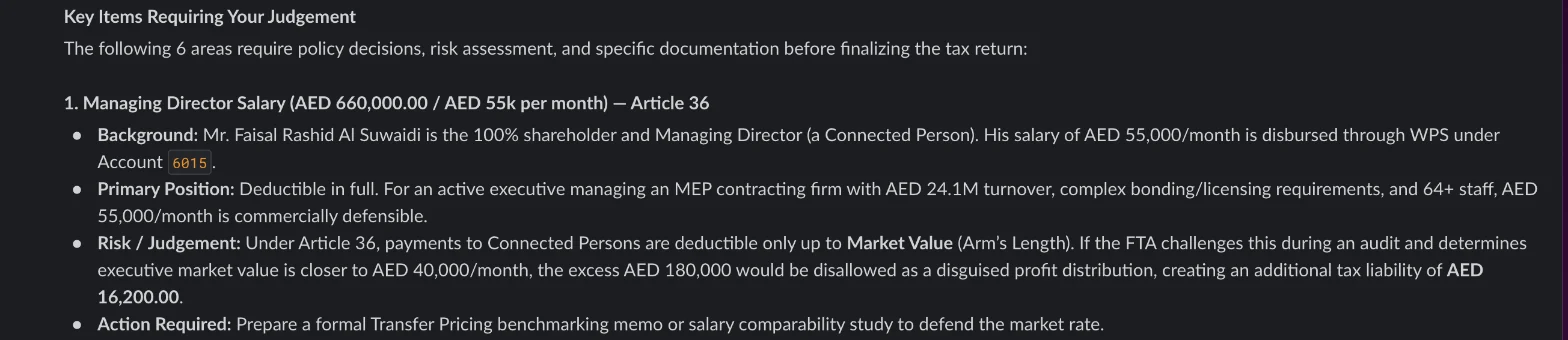
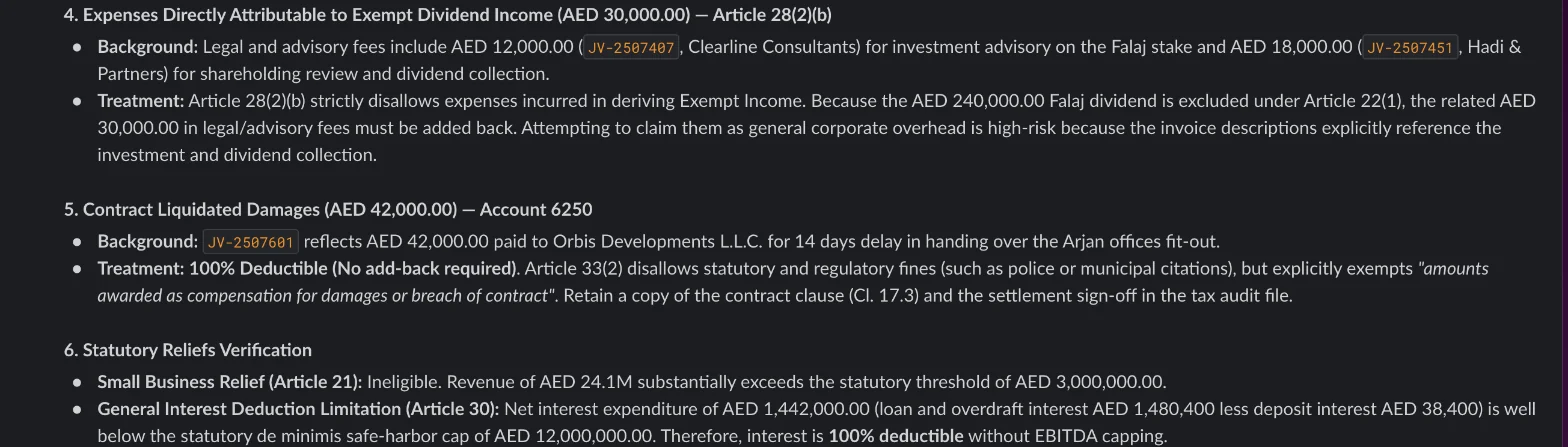
What you still check
- The owner's AED 660,000 salary against market pay for the role.
- The 60/40 split of the owner's phone, with a usage record behind it.
- Whether the parents' association donation, paid at the owner's request, is a business cost at all.
- Any article or guide the agent quotes, against the law and the FTA's own guides. It first gave the FTA's entertainment guidance the wrong title.
- The final figures on EmaraTax, which you enter and submit yourself.
Questions accountants ask
Is staff entertainment deductible for UAE corporate tax?
Yes, in full, if it is for the business. The 50% limit in Article 32 applies to entertaining customers, shareholders, suppliers and other business partners.
Are liquidated damages a fine?
Not for corporate tax. Article 33 blocks fines and penalties, but not amounts paid as compensation for damages or breach of contract.
Does the agent file the return?
No. It prepares the working and you file on EmaraTax yourself. It asks before it changes or submits anything.
Hand this job to an agent
Bring one of your own files to a 30-minute call and watch an agent do it.
Book a 30-min demo