Short answer: Under section 43B(h), a purchase from a micro or small supplier that you pay after the MSMED Act limit is allowed only in the year you pay. The limit is the agreed credit days up to 45, or 15 days with no agreement. Medium suppliers and traders are outside it. Clause 22 of Form 3CD, as substituted from AY 2025-26, reports the year's total due to micro and small suppliers, the part paid on time and the part disallowed.
Every purchase from a micro or small supplier now carries a tax audit question: was it paid inside the MSMED Act limit? If it wasn't, and the bill was still open at year end, the expense moves to the year you pay.
Here is the method from a recent tutorial, then an agent working through a year of creditors for a sheet-metal company in Faridabad. It got every bill right, but used the old clause 22 layout until it was told the clause had changed.
The tutorial this is based on
Tax Audit Practical Class – Clause 22 | MSME Reporting in Form 3CD | AY 2026-27 by eFileEase, published 21 August 2026 (in Hindi). Covers the time limits, who counts as a supplier, 43B(h) and the amounts to report, and shows the clause in Computax. Most of it is slides: the working is described rather than shown, and its examples use FY 2024-25 dates. We added a full working.
How do you work out the 43B(h) disallowance and clause 22?
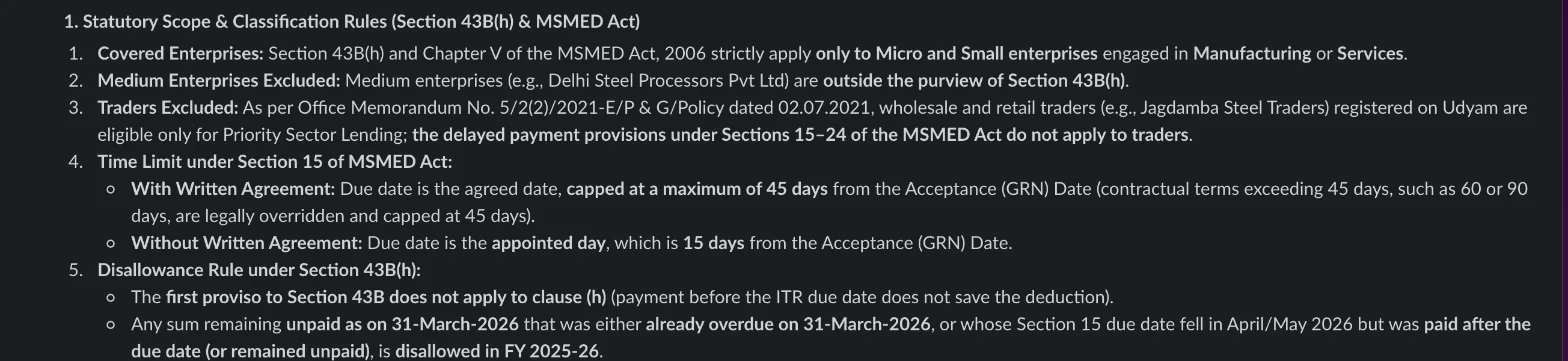
- List the suppliers that count: micro or small on the Udyam certificate, and a manufacturer or service provider. Medium enterprises are out, and so are traders, whose Udyam registration is only for priority-sector lending (Ministry of MSME memorandum of 2 July 2021).
- Pull each such supplier's bills from Tally with the acceptance date (from the goods received note), the bill value and the payment date.
- Work out each bill's due date: the agreed credit days, capped at 45 days from acceptance, or 15 days if there is no written agreement. The video's example: accepted on 20 March with no agreement, so the last date is 4 April.
- Mark each bill as paid on time, paid late within the year, or open at 31 March. For the bills open at year end, check the April-May bank statement for when they were paid.
- A bill open at 31 March and not paid by its due date is disallowed this year and allowed in the year you pay. The usual grace period up to the return due date doesn't apply to 43B(h). Bills paid late but within the year are allowed, though MSMED interest runs on them.
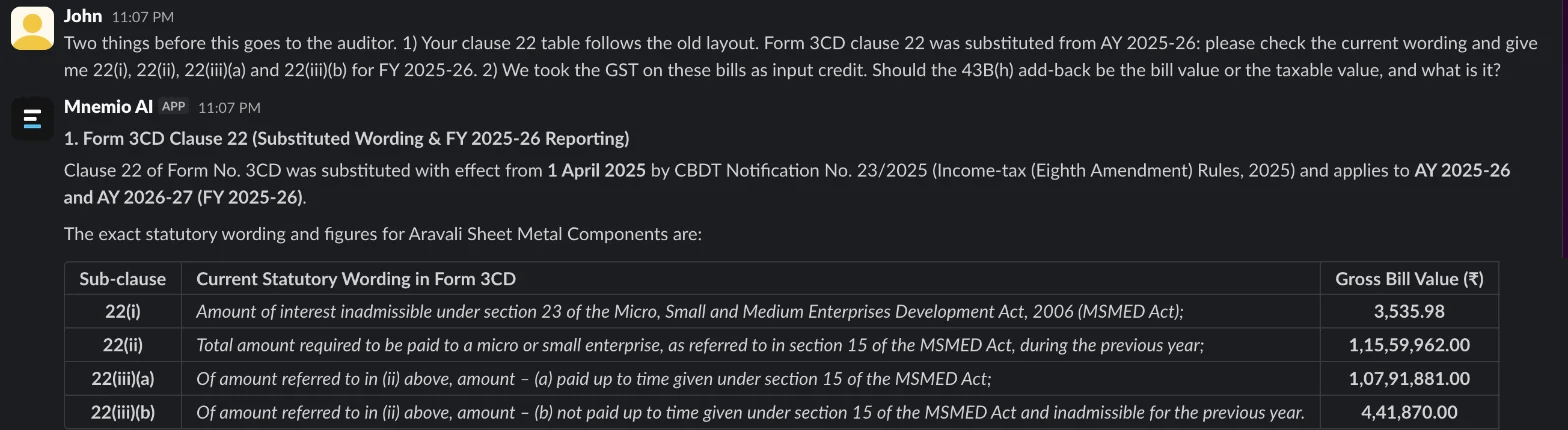
- Fill clause 22: (i) the interest under the MSMED Act, which isn't deductible; (ii) the total required to be paid to micro and small suppliers in the year; (iii)(a) the part paid within the time; (iii)(b) the part not paid in time and disallowed for the year.
- Where certificates or acceptance dates are missing, take a management representation, confirm with a sample of suppliers and say so in the report.
Where it usually goes wrong
- Using the agreed 60 or 90 days instead of capping them at 45.
- Including a medium supplier, or a trader because it has a Udyam number.
- Disallowing bills that were paid late but inside the year.
- Adding back the GST along with the bill when the GST was taken as input credit.
- Treating a supplier tagged MSME in Tally as one without seeing its certificate.
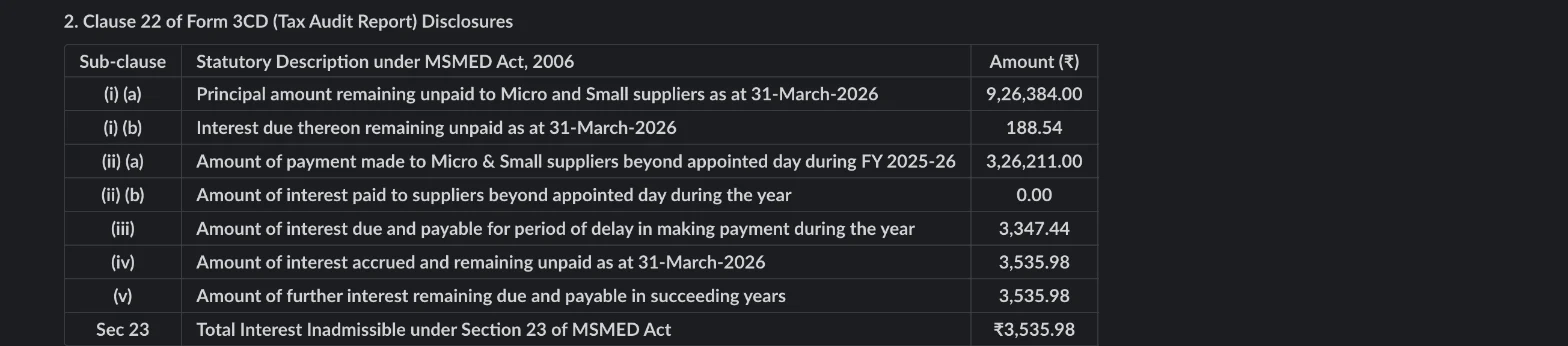
- Filling clause 22 in the layout used before AY 2025-26.
How an AI agent does it from Slack
We gave the agent three files for a made-up Faridabad company, Aravali Sheet Metal Components: the creditors ledger bill by bill for FY 2025-26 (205 bills from 30 suppliers, with acceptance and payment dates), the supplier master with Udyam details and agreed credit days, and the April-May 2026 bank statement. Every company, name, tax number and amount in these files is made up. The agent works in Slack, where it shows up as Mnemio AI, because Accountant AI is built on Mnemio AI.
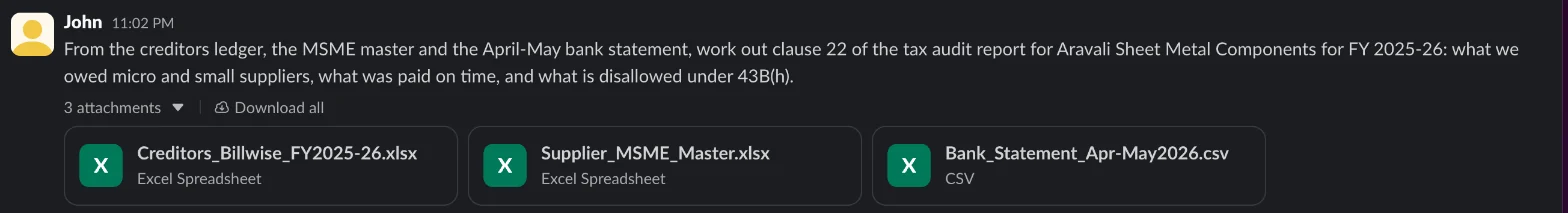
What the agent did
- Read the 205 bills, the supplier master and the bank statement, and wrote a workbook.
- Left out the medium supplier, the trader and the supplier with no certificate, capped 60 and 90 days at 45, and used 15 days where there was no agreement.
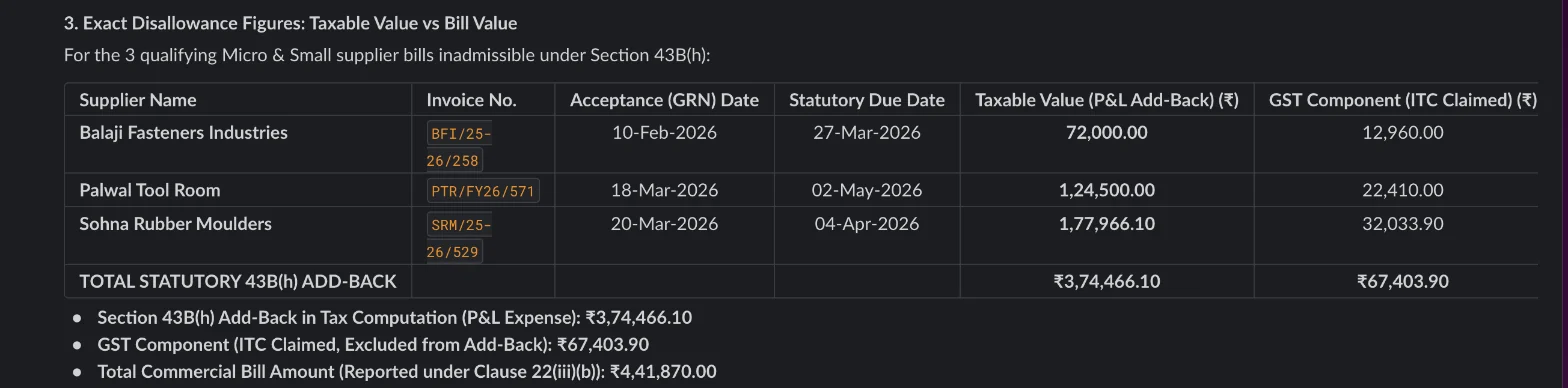
- Found three bills to disallow (₹4,41,870): Balaji paid on day 54, Sohna paid 36 days late and Palwal still unpaid on 31 May. It allowed Kundli's ₹3,40,000, paid on its due date, and three bills paid late within the year (₹3,26,211).
- Reported clause 22 in the old layout and worked out MSMED interest at 20.25%, a rate from before FY 2025-26.
- When told the clause had been substituted, it looked it up and gave 22(ii) ₹1,15,59,962, 22(iii)(a) ₹1,07,91,881 and 22(iii)(b) ₹4,41,870, all matching ours, and the add-back at taxable value, ₹3,74,466.10. 22(i) still used the 20.25% rate.
What it found
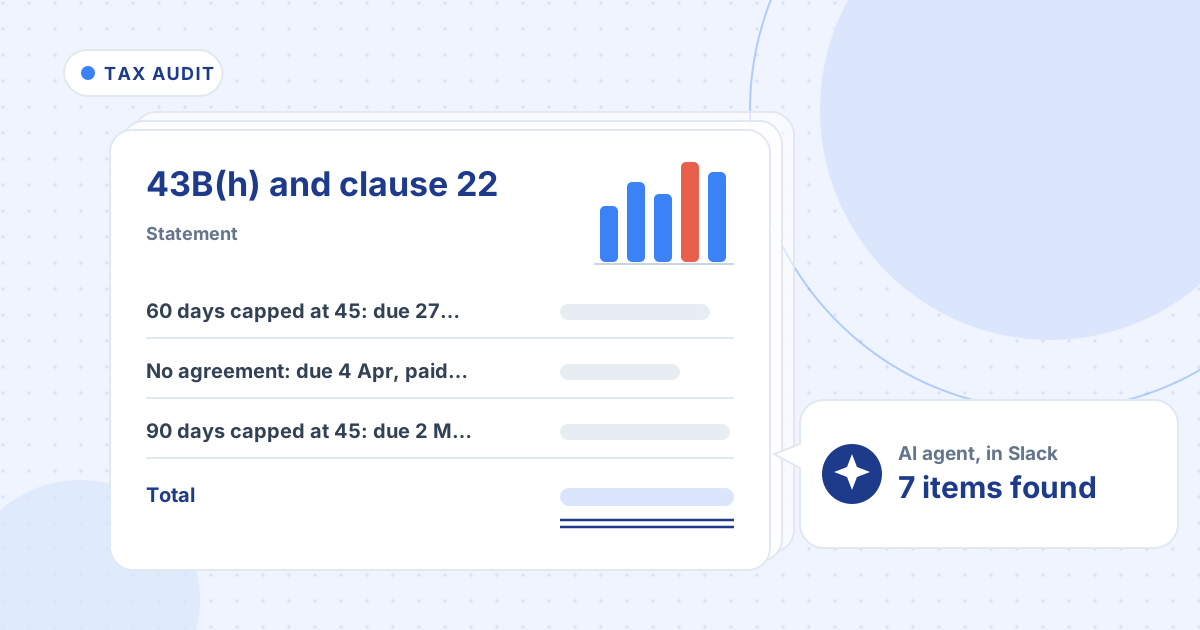
| Bill | Why | 43B(h) |
|---|---|---|
| Balaji Fasteners BFI/25-26/258 | 60 days capped at 45: due 27 Mar, paid 5 Apr | Disallowed ₹72,000 |
| Sohna Rubber SRM/25-26/529 | No agreement: due 4 Apr, paid 10 May | Disallowed ₹1,77,966.10 |
| Palwal Tool Room PTR/FY26/571 | 90 days capped at 45: due 2 May, unpaid | Disallowed ₹1,24,500 |
| Kundli Wire KWP/25-26/247 | No agreement: due and paid 4 Apr | Allowed |
| Delhi Steel Processors | Medium enterprise | Out of scope |
| Jagdamba Steel Traders | Trader with a Udyam number | Out; auditor to confirm |
| Om Sai Engineering | Tagged MSME, no certificate | Ask for the certificate |
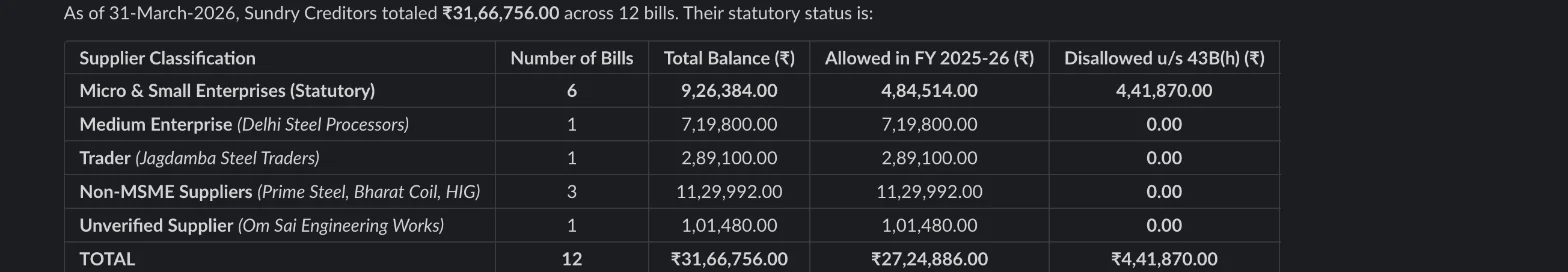
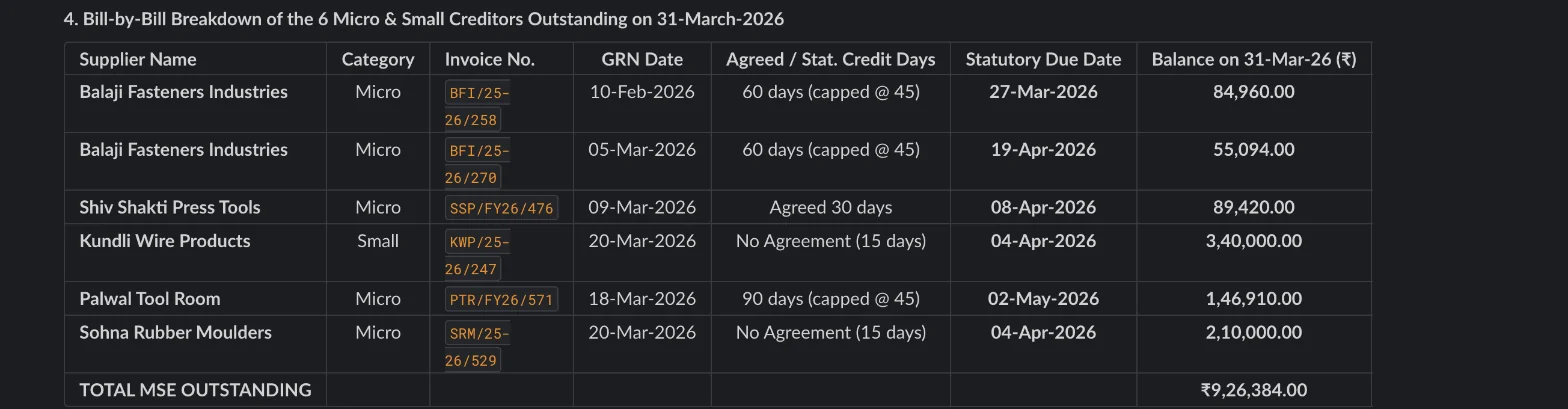
What you still check
- The MSMED interest for 22(i). The agent used 20.25%. Work it out at three times the RBI bank rate in force, compounded monthly; the bank rate fell from 6.25% to 5.50% during FY 2025-26.
- Each supplier's status from its Udyam certificate: Om Sai Engineering is tagged MSME in Tally with no certificate on file, and the auditor should confirm the trader.
- Acceptance dates from the goods received notes. Every due date depends on them.
- The clause 22 layout in the utility you file with. The agent used the old one until it was told.
Questions accountants ask
What is the time limit for paying MSME suppliers under 43B(h)?
The limit in section 15 of the MSMED Act: the credit days in your written agreement, up to 45 days from acceptance, or 15 days if there is no agreement. Pay after that and the expense is allowed only in the year you pay.
Are traders covered by 43B(h)?
No. Since July 2021 traders can register on Udyam, but only for priority-sector lending; the delayed-payment provisions don't apply to them. Medium enterprises are outside 43B(h) too.
Is the 43B(h) add-back the bill value or the taxable value?
If you took the GST as input credit, only the taxable value went to profit and loss, so that is what you add back. Clause 22 reports the amounts payable, at bill value. Practice varies, so agree it with your auditor.
Hand this job to an agent
Bring one of your own files to a 30-minute call and watch an agent do it.
Book a 30-min demo